燃油成本飙升冲击承运商利润率
燃油成本可能是运输业中最容易被误解的项目之一。它对承运人的影响是不均衡的,而且比大多数人预期的更为微妙。帖子:燃油成本飙升冲击承运商利润……
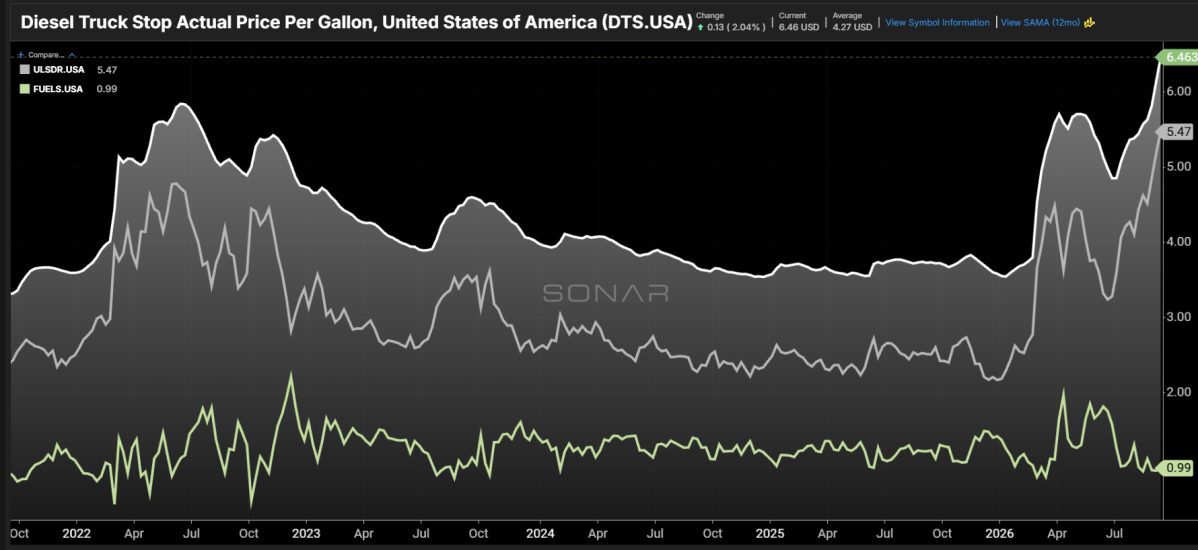
Chart of the Week: Daily Retail Diesel Price, Wholesale Diesel Price, Retail-Wholesale Fuel Spread – USA SONAR: DTS.USA, ULSDR.USA, FUELS.USA
Last week, J.B. Hunt issued a rare warning of a 5% to 10% earnings headwind in the third quarter, driven by rising fuel and driver costs. Retail diesel prices (DTS) rose roughly 31% from July 5 to September 17, while wholesale prices (ULSDR) climbed at more than twice that pace, narrowing the retail-wholesale spread by about 48% over the same period. When that spread shrinks, larger carriers that buy fuel at wholesale levels take the hit — though they typically make it back when fuel prices decline. The market punished J.B. Hunt for what looks like giveback in Q3 from a potentially bloated Q2, not necessarily a long-term threat.
The first thing to understand is how fuel spikes affect larger fleets. Many large fleets have the scale to negotiate fuel purchases at a discount to the retail price. Most of these “discounts,” though, are actually premiums to the wholesale — commonly called “rack” — price: something like rack plus 2%. So when the rack price is $3.89, the rate the carrier pays is $3.97.
Most carriers pass some portion of fuel costs to customers through a fuel surcharge, to avoid getting caught out when diesel prices swing sharply. Because most fuel surcharges are based on the retail price, this leaves the carrier some buffer to work with when fuel costs fluctuate.
This buffer varies with how competitive the pricing environment is and how stable fuel costs have been. When the market is competitive and fuel is stable, carriers tend to lower their base rates, exposing themselves to more fuel price volatility. When the market is tight, they can raise base rates, reducing their long-run exposure to fuel price swings.
This is the core problem J.B. Hunt is running into in its dedicated and intermodal businesses. These rates are negotiated over a much longer term and don’t get renegotiated intra-cycle. Most of these contracts were set before the recent market flip, which occurred in late 2025 and early 2026.
Because those rates were priced competitively to win business in a tight-margin market, J.B. Hunt carries more exposure to swings in operating-cost inflation. The fuel spread (FUELS) between retail and wholesale diesel is a good data point that illustrates this.
Wholesale diesel prices, as with most commodities, are far more volatile than their retail counterparts, as the chart above shows. Retailers buy in bulk and can hold prices steadier over time, whereas wholesale is more of a free market that’s negotiated daily.
In an inflationary market, wholesale diesel costs rise faster than retail prices. That means carriers are buying fuel at a higher cost than what their fuel surcharge — based on the slower-moving retail figure — has caught up to yet. This shows up as a lower fuel spread, which has averaged just above $1 per gallon since early July. Compare that to the roughly $1.25 average spread from 2022 through March of this year, and you can see the margin erosion if fuel surcharge tables and base rates held steady.
The spread from April to July averaged above $1.50 per gallon, meaning carriers largely benefited. So while the market may have overly celebrated J.B. Hunt in Q2, there’s some giveback in Q3 — but over the long run, it’s relatively meaningless.
What about smaller fleets?
Small fleets that don’t buy fuel at wholesale prices face a different problem: rising retail prices are hard to pass through on the spot market, especially in a competitive environment. Today’s market isn’t quite that competitive, but it still isn’t allowing much further rate inflation, as the chart below illustrates. As with any commodity, the end consumer will only absorb added cost if they have no other option.
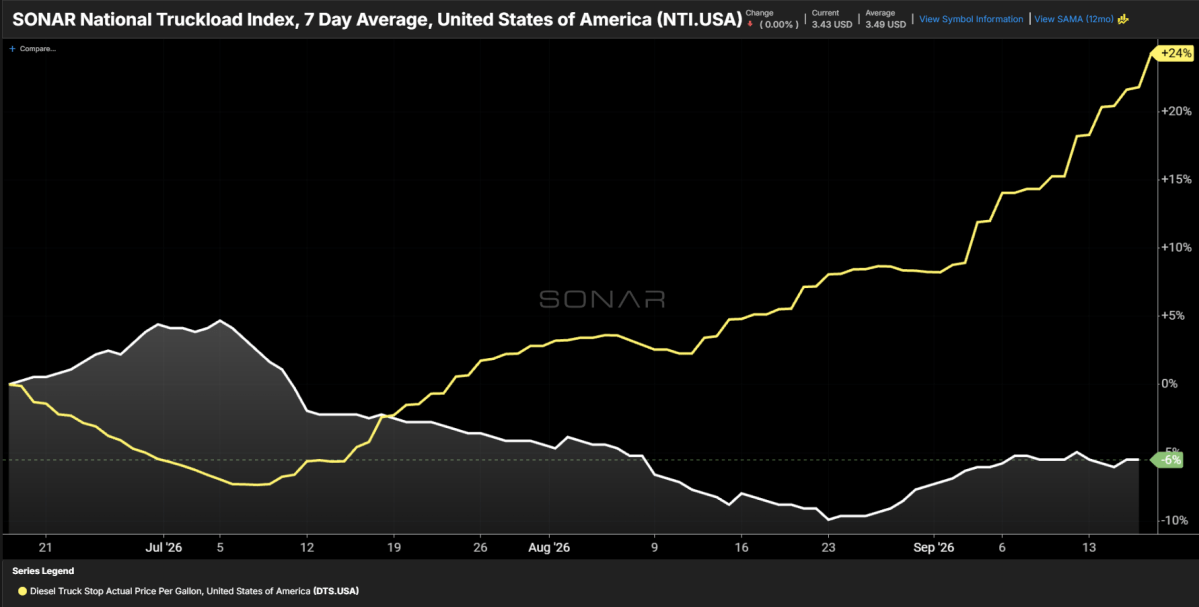
The retail diesel price (yellow) — what many smaller fleets without purchasing power pay — is up roughly 24% over the past three months, while spot rates are down about 6%. That’s not necessarily a sign of losing money, but it does suggest margin erosion.
The hard part for small carriers is that there’s no guarantee they’ll recoup that margin loss later — it’s entirely market-dependent.
About the Chart of the Week
The FreightWaves Chart of the Week is a chart selection from SONAR that provides an interesting data point to describe the state of the freight markets. A chart is chosen from thousands of potential charts on SONAR to help participants visualize the freight market in real time. Each week a Market Expert will post a chart, along with commentary, live on the front page. After that, the Chart of the Week will be archived on FreightWaves.com for future reference.
SONAR aggregates data from hundreds of sources, presenting the data in charts and maps and providing commentary on what freight market experts want to know about the industry in real time.
The FreightWaves data science and product teams are releasing new datasets each week and enhancing the client experience.
To request a SONAR demo, click here.
The post Fuel cost spike hits carrier margins appeared first on FreightWaves.